Financial Infidelity Recovery: How to Rebuild Trust
Recovering from financial infidelity takes three things in order: a complete, verified picture of the money, an honest conversation about why the secrecy happened, and new habits that make hiding things unnecessary. Most couples can get through it, but trust returns through repeated, boring transparency, not through one big apology. This guide walks through each stage, including what to do when the betrayal is tied to hidden debt, a secret account, or an affair.
TL;DR
- Get the facts first: review statements, tax returns and credit reports together before you try to resolve anything emotionally.
- Separate the money from the meaning. The number matters, but the broken trust is what drives the pain.
- Replace secrecy with structure: a scheduled money meeting, shared visibility into accounts, and agreed limits on solo spending.
- Get a therapist involved when the conversations keep turning into fights, or when the deception is large, repeated, or tied to addiction or an affair.
- Expect months, not days. Progress is measured by consistent behavior over time.
Table of Contents
- What financial infidelity and financial betrayal actually look like
- Step 1: Get the full financial picture
- Step 2: Have the honest conversation
- Step 3: Build transparency that lasts
- Step 4: Repair the emotional side
- How long does recovery take?
- When to get professional help
- Tools to help you through it
- FAQ
- Sources
What financial infidelity and financial betrayal actually look like
Financial infidelity means deliberately hiding or lying about money from a spouse or partner. The U.S. Government Accountability Office describes motives that range from nonmalicious disagreements about how to pay for purchases to intentional deceit involving divorce, an affair, addiction, or hidden debt. That range matters. A secret $40 shoe habit and a drained retirement account are not the same offense, though both can feel like a violation of the marriage.
Common forms include:
- A secret credit card, loan, or line of credit
- A hidden checking or savings account
- Understating or concealing income
- Gambling, shopping, or day-trading losses kept quiet
- Lying about what a purchase cost or what it was for
- Supporting someone else financially, such as a relative or an affair partner
- Taking money out of a joint or retirement account without consent
The consequences can be serious. The GAO reported in April 2026 that victims of financial infidelity, such as a spouse who removes retirement funds without consent, can face severe consequences, including delayed retirement or even homelessness.
How common it is, and what it does to marriages
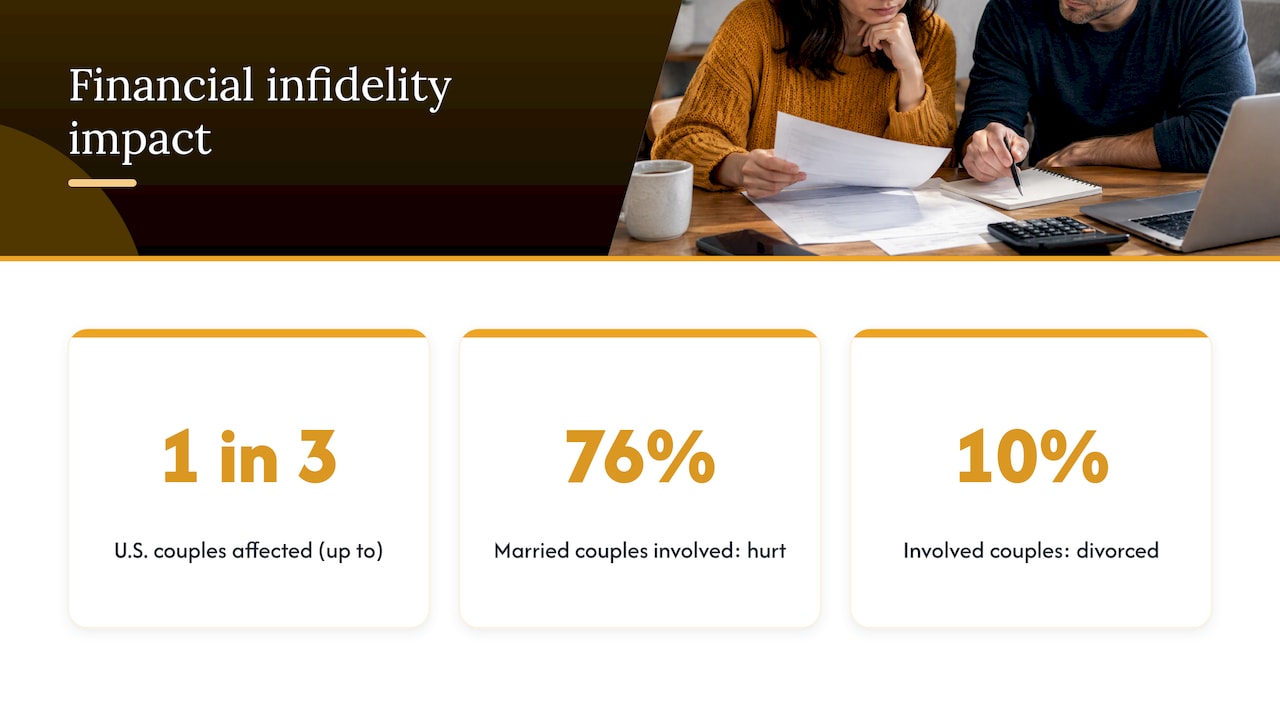
You are not unusual if this is happening to you. A January 2022 U.S. News & World Report survey found that as many as one in three U.S. couples deal with financial infidelity. The same report cites a 2018 study in which 76% of married couples involved in financial infidelity said it hurt their relationship, and 10% divorced as a result.
Research summarized by Northeastern University links financial infidelity to lower relationship satisfaction, in part because partners end up with misaligned goals. It also notes that a spouse may be legally responsible for a partner’s debt, which is why the practical side of recovery cannot wait.
Step 1: Get the full financial picture
Do this before the big emotional conversation. If you confront your spouse with a half-formed suspicion, you will get a half-formed answer. If you have the documents, you can ask better questions and hear fewer excuses.
Gather the paperwork
Divorce lawyer William Beslow, quoted by AARP, recommends reviewing all financial paperwork to confirm suspicions: bank records, credit card bills, income tax returns, and investment statements. Start with what you can already see, such as joint account activity, mail, and the household tax return.
Pull credit reports
Credit reports show accounts you may not know exist. The Federal Trade Commission explains that all three nationwide credit bureaus now let you check your report once a week for free at AnnualCreditReport.com, and that this is the only authorized site for the free reports. Each spouse should pull their own. Look for unfamiliar accounts, collections, recent inquiries, and balances that are higher than you expected.
If the person who hid things is willing, ask them to pull their own reports and review them with you in the same room. That turns discovery into disclosure, which is a very different experience for both of you.
Know when to bring in a professional
AARP’s guidance is that if the numbers still do not add up, or the true picture remains unclear, hiring a forensic accountant is an option. Given the legal exposure on shared debt, a consultation with a family law or financial attorney is also reasonable when the amounts are large, especially if separation is on the table.
Do a “full disclosure” session
Once you have the documents, ask the partner who hid things to complete one full disclosure: every account, every debt, every ongoing commitment, in writing, with statements attached. The rule is simple. Anything that surfaces later counts as a new betrayal, so it is far better to over-disclose now. This is a request, not an ambush, and it works best when you agree on a time and place in advance.
Step 2: Have the honest conversation
Money conversations after a betrayal go wrong in predictable ways. One partner attacks, the other defends, and the numbers disappear under the emotion. A few ground rules help.
- Pick a calm time. Not at midnight, not in front of the kids, not right after a bill arrives. Agree on 45 to 60 minutes.
- Start with the impact, not the amount. The partner who was deceived describes what it did to their sense of safety: “I felt like I was living with someone I could not read.”
- The partner who hid things listens first. No explaining, no “but you also…” until the other person feels heard. Then reflect back what you heard.
- Then ask why. Not as an accusation, but as a real question: what were you afraid would happen if I knew?
- Name what each of you needs. One concrete request each, such as “I need to see statements monthly” or “I need to know you will not be punished for telling me about a mistake.”
- Stop when it escalates. Agree on a pause word and a time to resume, ideally within 24 hours.
Understand what the secrecy was protecting
Secrets about money are rarely just about money. They often protect shame about debt, fear of a partner’s anger, a need for autonomy, or a belief inherited from childhood about what money means. Writing a joint “money story,” where each partner describes how they learned to think about money and what they want from it, is one approach some couples use to understand each other’s beliefs and goals.
Understanding a reason is not the same as excusing the behavior. The partner who hid money still owns the choice. But a couple that understands the fear behind the secrecy can design a system that removes the need for it. Our guide to money fights in marriage shows how to get to shared values in a short, structured conversation.
Step 3: Build transparency that lasts
Trust is rebuilt when your spouse can verify, over time, that what you say matches what is true. The goal is not permanent surveillance. It is a period of visible honesty that eventually makes checking unnecessary.
A practical transparency framework
| Area | What it looks like | Why it helps |
|---|---|---|
| Account visibility | Both partners have login or read-only access to every account | Removes the possibility of hidden balances |
| Weekly check-in | 15 minutes on spending, upcoming bills and anything unusual | Keeps small things from becoming secrets |
| Monthly money meeting | 45 to 60 minutes on budget, debt progress and goals | Gives the couple a shared direction |
| Spending threshold | An agreed amount (for example $100) above which you tell each other first | Preserves autonomy without surprises |
| Personal allowance | A set amount each person can spend with no explanation | Reduces the pressure that drives hiding |
| Credit reports | Both pull reports on a set schedule and compare notes | Catches new accounts early |
The thresholds are yours to set. What matters is that both of you chose them, and that the person who was deceived does not feel the agreement is a one-sided punishment, nor that the person who hid things is being treated as a permanent suspect.
Make a debt plan together
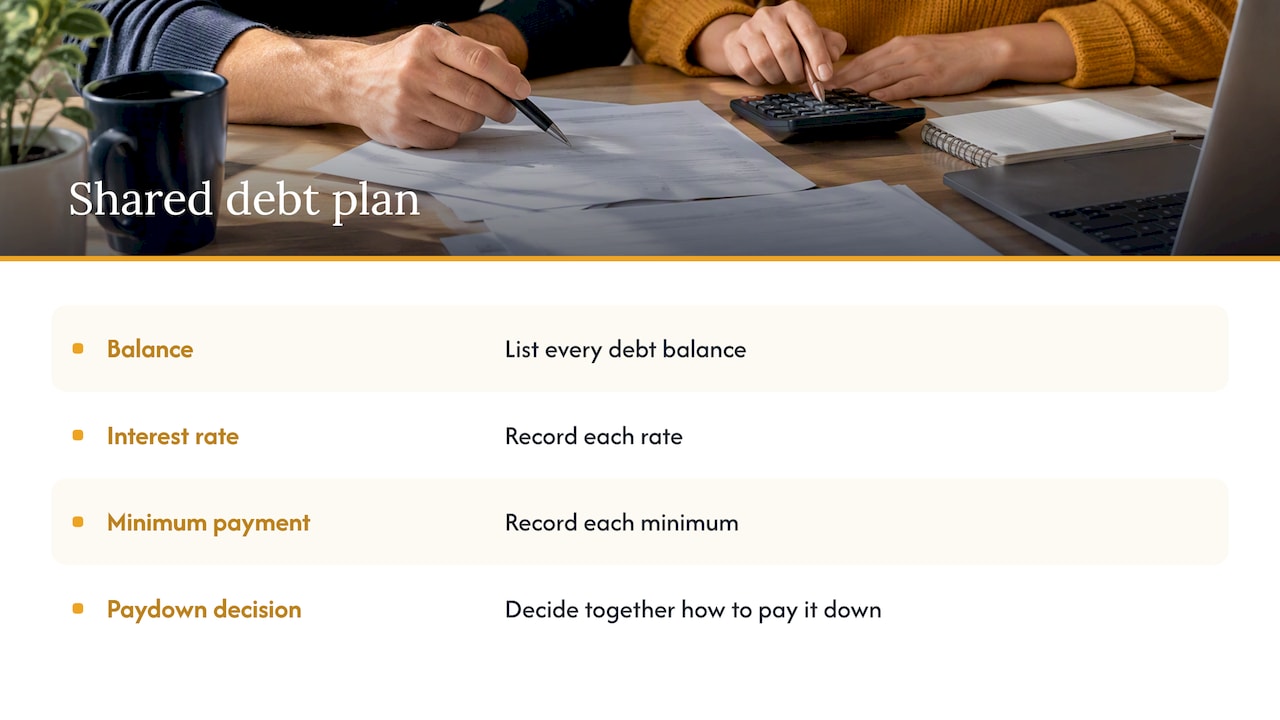
If hidden debt is part of the picture, list every balance, its interest rate and its minimum payment, then decide together how to pay it down. Having a plan changes the emotional tone from “what did you do” to “what do we do next.” If the debt is overwhelming, a nonprofit credit counselor or a financial professional can help structure it.
Celebrate consistency
Small wins count. Thirty days of on-time disclosure, a monthly meeting that ended without a fight, an uncomfortable purchase reported before it happened: say so out loud. Rebuilding is mostly an accumulation of moments when the partner who broke trust chose honesty when it was costly.
Step 4: Repair the emotional side
Many couples fix the budget and still feel distant. That is normal. The deceived partner may have flashes of anger months later, may check accounts compulsively, or may pull back from affection. The partner who lied may feel shame and stay defensive or overly apologetic.
A few things help:
- Allow questions. The deceived partner will need to ask the same things more than once. Answer calmly and consistently each time.
- Show, don’t just say. Sorry means more when it comes with changed behavior.
- Rebuild positive time. Plan something that has nothing to do with money. Our friends’ list of couples retreat ideas is a good place to look for ways to reconnect away from home once the first hard conversations have happened.
- Watch for the pattern behind the pattern. If money lies sit alongside secrecy in other areas, it is worth looking at the wider trust problem.
If the betrayal overlaps with an affair, the money and emotional repair run in parallel. Our pages on intimacy after infidelity, forgiveness after infidelity and jealousy after infidelity cover what to expect.
How long does recovery take?
No reliable figure applies to every couple, and anyone who promises a timeline is guessing. What tends to shape the pace is the size of the deception, whether it was a one-time event or a pattern, how fully the disclosure was made, and whether both partners keep showing up to the process.
A useful way to track progress is by behavior, not by how you feel on a given day:
- Disclosure is voluntary instead of dragged out.
- Money meetings happen on schedule and stay civil.
- The deceived partner checks less, and the check-ins feel lighter.
- Both partners can talk about the event without it taking over the evening.
Setbacks are part of the process. A new surprise is serious and should be addressed directly, but a bad week after a good month does not mean the work has failed.
When to get professional help
Consider a therapist or counselor when:
- Every money conversation turns into a fight, or one of you shuts down.
- The deception was large, repeated, or involved an addiction such as gambling.
- The financial secrecy came with an affair or another betrayal.
- One partner is thinking about leaving and you both want a structured attempt first.
- The deceived partner is showing signs of ongoing anxiety, depression or sleeplessness. In that case, see a licensed mental health professional or your doctor.
If debt, taxes or shared legal liability are involved, add a financial professional or attorney. Therapy handles the relationship, and they handle the numbers. You can read more about what to expect from couples therapy after betrayal and about online marriage counseling after infidelity.
Our perspective
After working with thousands of couples, we see the same thing again and again: the spreadsheet is rarely the real problem. When a spouse discovers hidden money, the question underneath is “Can I believe you?” And the partner who hid it is usually carrying shame, fear of conflict, or a belief that telling the truth would cost them the relationship.
That is why we built the F.I.G.H.T. Plan® as a step-by-step system rather than a set of tips. It gives you a structure for the conversations couples find hardest: how to raise the topic without an attack, how to listen without defending, how to regulate when your heart is racing, and how to turn an agreement into a habit. We think couples can make real progress with the right tools and a plan, and that you do not have to wait until things collapse to start.
If you do one thing this week, schedule the first money meeting and agree on its ground rules before you open a single statement.
Carlos
Tools to help you through it
If you want a structured path rather than improvising these conversations, we offer options at different levels:
- Workbooks. The F.I.G.H.T. Plan workbook is $14.99 to $25.00, and the F.I.G.H.T. Plan Couples Conflict Toolkit is $27.00. Both give you conversation scripts and exercises you can work through together at home.
- Courses. Stop the Fighting: The Couples Communication & Conflict Resolution Course is $149.00, and Fight Less Love Again is $47.00.
- Coaching. Our VIP Private Coaching Session package of four sessions is $997.00, and the 6 Hours Couples Intensive is $1,995. Details on online couples coaching and the intensive are on those pages.
If the financial betrayal came with an affair, our RESTORE® infidelity recovery counseling page explains that approach. You can browse everything in our shop.
FAQ
Can a marriage survive financial infidelity?
Yes, many couples do recover, especially when the hiding partner takes full responsibility, discloses everything, and both partners commit to new money habits. The odds are better when the deception is addressed early and honestly. Research cited by the BBC found that 10% of couples with financial infidelity in a 2018 study divorced, so a large majority stayed together, although most reported a negative effect on the relationship.
Is financial infidelity grounds for divorce?
That depends on your state and your circumstances, and you should ask a family law attorney in your state. Hidden debt can also create legal exposure for a spouse, and Northeastern’s research summary notes a spouse may be legally responsible for a partner’s debt. If you are considering separation, get legal advice before you move money or close accounts.
Should I check my spouse’s accounts without telling them?
Start with what you are entitled to see, such as joint accounts, shared tax returns and your own credit report. Reviewing paperwork is the first step suggested in AARP’s guidance. Accessing a spouse’s individual accounts or passwords without permission can create legal and trust problems of its own, so talk to an attorney before you go there.
How do I bring it up without starting a fight?
Choose a calm time, start with how the discovery affected you, and ask a real question about what happened. Agree in advance on a pause word if things heat up. If you cannot get through a conversation without escalation, a couples therapist or coach can guide the first few.
What if my partner will not be honest or won’t change?
If disclosure is partial, new secrets keep appearing, or your partner refuses to take part in any plan, trust cannot rebuild. Consider individual therapy for yourself, consult an attorney about protecting your finances, and decide what boundaries you need. You cannot do the repair for both of you.
Sources
- Financial Infidelity: Removing Money from a Retirement Account (U.S. Government Accountability Office)
- How Financial Infidelity Can Harm Relationships (Northeastern University)
- The ‘financial infidelity’ that can sink couples (BBC Worklife)
- Telltale Signs of Spouses Who Lie About Money (AARP)
- Free Credit Reports (Federal Trade Commission)
- Can Your Marriage Bounce Back from Financial Infidelity? (goop)
Recommended
- Intimacy After Infidelity: How to Rebuild It, Step by Step
- 30–90 Day Behavior First Transparency Plan After an Affair
- Therapy Backed Behavior First Steps to Repair an Emotional Affair
- 6 Neuroscience Backed Steps to Stop Jealousy After Infidelity